Choose a section or paragraph
A major U.S. bank is taking another step toward integrating cryptocurrency technology into everyday financial services.
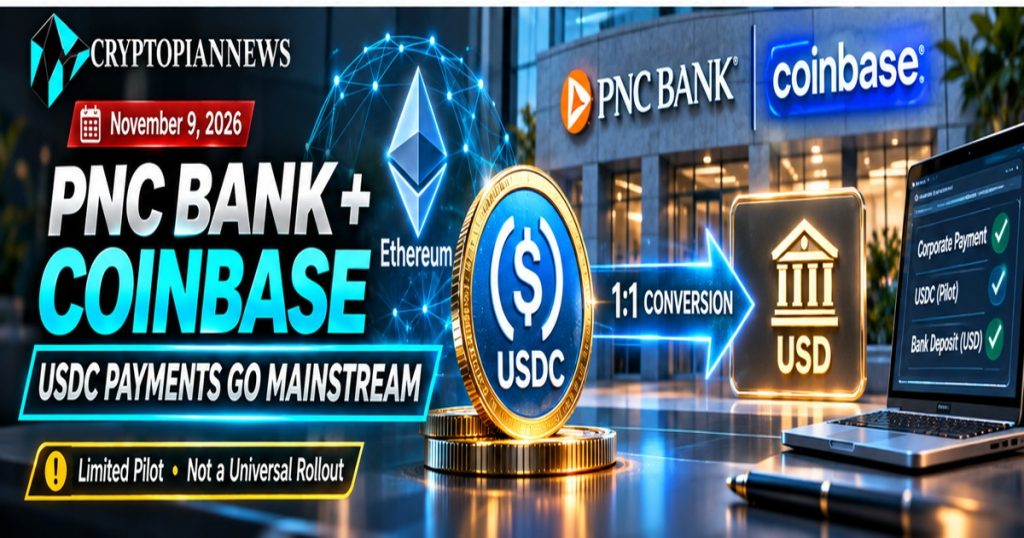
PNC Bank announced on November 9 that it is working with Coinbase to allow eligible corporate and institutional clients to receive payments using USDC, a dollar-backed stablecoin issued by Circle.
Under the limited pilot program, participating businesses can receive USDC on the Ethereum blockchain. The payments are then automatically converted into U.S. dollars and deposited into designated PNC bank accounts.
The announcement provides a practical example of how banks are exploring blockchain payments without requiring customers to manage cryptocurrency balances directly.
But does this mean stablecoins are finally becoming part of mainstream banking?
What Did PNC Bank and Coinbase Announce?
PNC Bank’s new service is designed for eligible corporate and institutional banking customers.
Coinbase supplies the underlying stablecoin payment infrastructure, while PNC provides traditional banking, deposit accounts and treasury management services.
The process is intended to be straightforward.
A participating business receives a payment denominated in USDC. The stablecoin is processed using Coinbase’s payment infrastructure and automatically converted into dollars before the funds arrive in the business’s PNC deposit account.
This means that eligible companies can accept certain blockchain payments while continuing to manage their money through conventional bank accounts.
The initial program is limited to selected clients, rather than a nationwide launch for all PNC customers.
Why Are Banks Interested in Stablecoins?
Traditional international payments can involve multiple financial institutions, intermediary banks, processing requirements and settlement schedules.
Stablecoins offer a different technological approach.
Dollar-backed digital tokens can move across supported blockchain networks, potentially allowing participating businesses to transfer value outside normal banking hours.
For companies with international operations, the possibility of faster transfers is particularly attractive.
However, blockchain transfers are only one part of a complete payment process.
Compliance checks, conversion into fiat currency, operational costs and banking procedures can still affect the time required for funds to become available.
PNC has not publicly disclosed detailed fee schedules, participating-client numbers or independently measured settlement-speed improvements for the new pilot.
Therefore, its benefits should be treated as objectives to be tested rather than fully proven outcomes.
Why Coinbase Is Important to the Partnership
Coinbase has been expanding its institutional services beyond cryptocurrency trading.
The PNC arrangement demonstrates how cryptocurrency companies can provide financial infrastructure to established banks.
Instead of requiring PNC to build every component of a blockchain payment system independently, Coinbase supplies payment technology that can connect stablecoin transactions with the bank’s existing operations.
The companies previously established a broader relationship involving cryptocurrency-related services.
The latest pilot extends that cooperation into corporate payments.
For Coinbase, successful adoption could strengthen its position as a provider of digital asset infrastructure.
For PNC, the partnership offers a way to test new payment services while retaining conventional bank-account relationships.
Why Ethereum Matters
The pilot uses USDC transfers on Ethereum.
Ethereum is one of the major blockchain networks supporting stablecoins, decentralized applications and tokenized financial assets.
Its role in the PNC program shows that blockchain technology can be useful even when the end customer does not intend to hold cryptocurrency.
Businesses participating in the pilot receive conventional dollar deposits rather than being required to maintain USDC positions.
That distinction is important.
The technology behind a payment can use a public blockchain while the customer-facing product continues to operate through traditional banking channels.
However, the announcement does not establish that the pilot will directly increase demand for ETH or significantly affect Ethereum’s market price.
Could Stablecoins Replace Traditional Banking Payments?
Stablecoins could become an important complement to existing payment systems.
Their potential advantages include continuous blockchain availability, programmable transactions and the ability to transfer dollar-denominated tokens across supported networks.
But they also face limitations.
Businesses must consider cybersecurity, network reliability, regulatory requirements, fraud prevention, liquidity and the legal protections associated with different payment methods.
Traditional banking systems already provide established mechanisms for compliance, dispute handling and financial oversight.
The PNC pilot does not eliminate the need for those protections.
Instead, it explores how stablecoins can operate alongside the banking system.
Stablecoin Competition Is Increasing
USDC is not the only dollar-linked digital asset competing for institutional adoption.
The stablecoin sector includes other major products such as Tether’s USDT and Ripple’s RLUSD.
Cryptopian News recently covered how Ripple expanded its RLUSD stablecoin through Coinbase across XRP Ledger, Ethereum and Base.
That expansion reflects growing competition among issuers and infrastructure providers seeking institutional distribution.
The PNC partnership adds a different dimension to this trend: using stablecoins to connect business payments with traditional deposit accounts.
What Happens Next for PNC’s USDC Pilot?
Several questions will determine the program’s wider significance.
First, will PNC expand access beyond the initial group of eligible customers?
Second, will the bank disclose measurable improvements in payment speed or processing costs?
Third, can Coinbase and PNC demonstrate that the service operates reliably across different business-payment scenarios?
Finally, will other major banks introduce comparable stablecoin services?
A successful pilot could encourage wider adoption, but broader rollout is not guaranteed.
Final Takeaway: Crypto Technology Is Entering the Banking System
PNC Bank and Coinbase’s USDC pilot represents a meaningful step toward connecting blockchain payments with conventional financial services.
It is not evidence that cryptocurrencies are replacing banks.
Rather, it demonstrates how banks can incorporate selected blockchain capabilities into their existing products.
The distinction matters because mainstream adoption may increasingly occur through familiar financial services rather than requiring everyone to become a cryptocurrency trader.
For now, the pilot remains limited.
But its longer-term implications could be significant if corporate customers demonstrate sustained demand for blockchain-based payment infrastructure.
The next stage of cryptocurrency adoption may not happen on a trading exchange. It may happen inside a traditional bank account.
Sources and References
- PNC Bank — Official November 9 Announcement
- Coinbase — PNC Stablecoin Payment Partnership
- Reuters — PNC and Coinbase Stablecoin Pilot
Disclaimer: This article is informational and does not constitute financial advice.

- PNC Bank and Coinbase Bring USDC Payments to Traditional Banking: Is Crypto Going Mainstream? - November 10, 2026
- Chainlink Launches CustodySync With Anchorage Digital to Bring Institutional Capital Into DeFi - October 30, 2026
- Ripple’s RLUSD Lands on Coinbase as Stablecoin Expansion Accelerates - October 29, 2026